

Two things in life are certain. Death and Taxes. There are ways in which you can delay them by better health management (Death) and for Taxes by adopting smart strategies.
This happened in late 2023, a colleague of mine found himself in a financial bind. He and his wife had worked hard to build their future, including investing in a property in Perth. Like many others, they believed real estate was a great way to secure long-term wealth. But life threw them an unexpected curveball - when his wife lost her job due to a company restructure, and suddenly, their financial situation was in turmoil.
The burden of servicing both their home loan and the mortgage on their investment property became overwhelming. Every month, the numbers didn’t seem to add up. The stress of looming repayments, in high interest rates resulted in dwindling savings, and an uncertain future weighed heavily on them. He confided in me, worried and unsure of what to do next. Should they sell the investment property? Would they be forced to give up a long-term asset due to short-term cash flow issues?
In that moment, I suggested something simple - a PAYG withholding variation. It’s a strategy not often talked about but can make a massive difference for property investors especially in this high interest times. Instead of waiting for a lump-sum tax refund at the end of the financial year, he could adjust his tax withholding and receive the benefits of negative gearing throughout the year. This would increase his take-home pay and give him more breathing room to manage his mortgage payments.
He took that option and consulted his accountant. Within weeks, the adjustment was in place, and his cash flow improved significantly. The extra money in his pocket each month meant he could comfortably service both loans without dipping into emergency savings or selling off his investment property in distress.
Fast forward to today - he held onto the property, and thanks to market appreciation, his investment has gained over $100,000 in equity which happened to be more than one persons full time income for a year. What once seemed like an impending financial disaster turned into a profitable long-term decision, all because he had the right information at the right time.
There is Power of knowing our Options:
This story highlights an important lesson: sometimes, the problem isn’t a lack of money - it’s a lack of knowledge. There are countless strategies, adjustments, and financial tools that can help navigate tough situations, but many people don’t know they exist. The key is to seek advice, explore your options, and take action before making drastic decisions.
If you’re ever in a financial squeeze, don’t just assume that selling or cutting losses is the only way out. Sometimes, a small tweak can make all the difference.
I am personally using this option to increase my monthly take home pay. Largely because this extra cash on my offset account helping to lower my interest payments than getting it as a lump sum at the end of the year.
Also, I’m not against paying tax - I’m all for avenues and options in looking for optimising how much and when I pay them.
What is PAYG Schedule variation?
PAYG schedule variation allows property investors and others with significant deductions to adjust their tax withheld from their salary, providing more cash flow throughout the year instead of waiting for a large tax refund.
How do I go about doing it?
Follow the instructions laid out below.
This seems too hard for me and I’m scratching my head - what should I do?
Talk to your accountant and go from there.
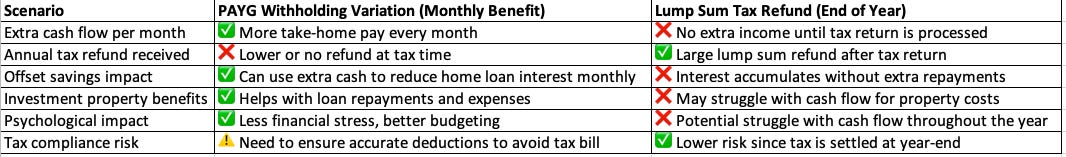
Here is a simple table of comparison between getting it monthly vs taking it as a lump sum at the end of the year!
Step-by-Step Guide: PAYG Withholding Variation (Section 221D Variation)
Step 1: Determine If a PAYG Withholding Variation is Right for You
A PAYG variation is beneficial if:
✅ You have substantial tax-deductible expenses (e.g., negatively geared investment properties, large work-related deductions).
✅ You consistently receive a large tax refund each year and prefer to smooth out cash flow throughout the year.
✅ Your expenses significantly reduce your taxable income, meaning too much tax is being withheld from your salary.
✅ Opt to increase your monthly take home and reduce your monthly interest paid on your borrowed amount.
Step 2: Gather Your Financial Information
Before applying, you’ll need:
🔹 Your latest payslips (for income details).
🔹 Expected rental income from your investment property.
🔹 Expected expenses (loan interest, property management fees, depreciation, etc.).
🔹 Last year’s tax return (if available, to compare deductions).
🔹 Your Tax File Number (TFN).
💡 Tip: If you're unsure about estimates, consult an accountant to ensure accuracy.
Step 3: Access the PAYG Withholding Variation Form
1️⃣ Go to the ATO website: ATO PAYG Withholding Variation
2️⃣ Download the PAYG Withholding Variation Application Form (NAT 2036) OR log into ATO Online Services via MyGov to submit electronically.
Step 4: Fill Out the Application Form
Key sections to complete:
🔹 Personal details – TFN, name, address, contact info.
🔹 Employer details – Company name, ABN, payroll contact details.
🔹 Income details – Salary, wages, investment income, rental income.
🔹 Deductions & Offsets – Loan interest, depreciation, rental property expenses.
🔹 Expected Taxable Income – This helps the ATO calculate your correct tax withholding rate.
💡 Tip: Ensure your estimates are realistic; overestimating deductions can result in a tax bill at the end of the year.
Step 5: Submit Your Application
📤 Online: Submit through MyGov > ATO Online Services > Tax > PAYG Withholding Variation.
📧 By Mail: Send the completed form to the address on the form.
⏳ Processing Time: The ATO typically processes applications in 28 days.
In my case it was 2 weeks!
Step 6: Inform Your Employer
✅ Once approved, the ATO will issue a PAYG Variation Notice to you and your employer.
✅ Your employer will adjust your tax withholding based on the new rates.
✅ You’ll start seeing higher take-home pay from your salary.
Key Things to Remember
⚠️ A PAYG variation does not reduce tax liability - it just spreads out your tax benefits across the year.
⚠️ The variation is valid for one financial year - you must reapply annually if needed.
⚠️ If circumstances change (e.g., salary increase, property expenses drop), notify the ATO to avoid underpaying tax.
P.S: None of these are financial advice - I am sitting and writing these contents from a place of my comfort which is suitable for me. I don’t know your personal circumstance and I don’t know your personal situations. It’s something you need to evaluate whether this is right for you. Please do your own research.
Credits / References: ChatGPT, Google, ATO, Learned experiences!