

Noah went Daddyyyy… I was like yeah! (sitting on my computer)
He went again Daddyyyyy… I was like WHATTTT!!!
he said - nothing!
Me and Noah have been spending a lot of time together eating each others brain - like literally!!
Given the school holidays with not much to do for him - I had to do come up with something for him to keep him sane and also me a little bit on a good headspace. So, we both got on to doing something simple science experiment and it reminded us both incredible opportunity to teach, bond and have fun in the process.
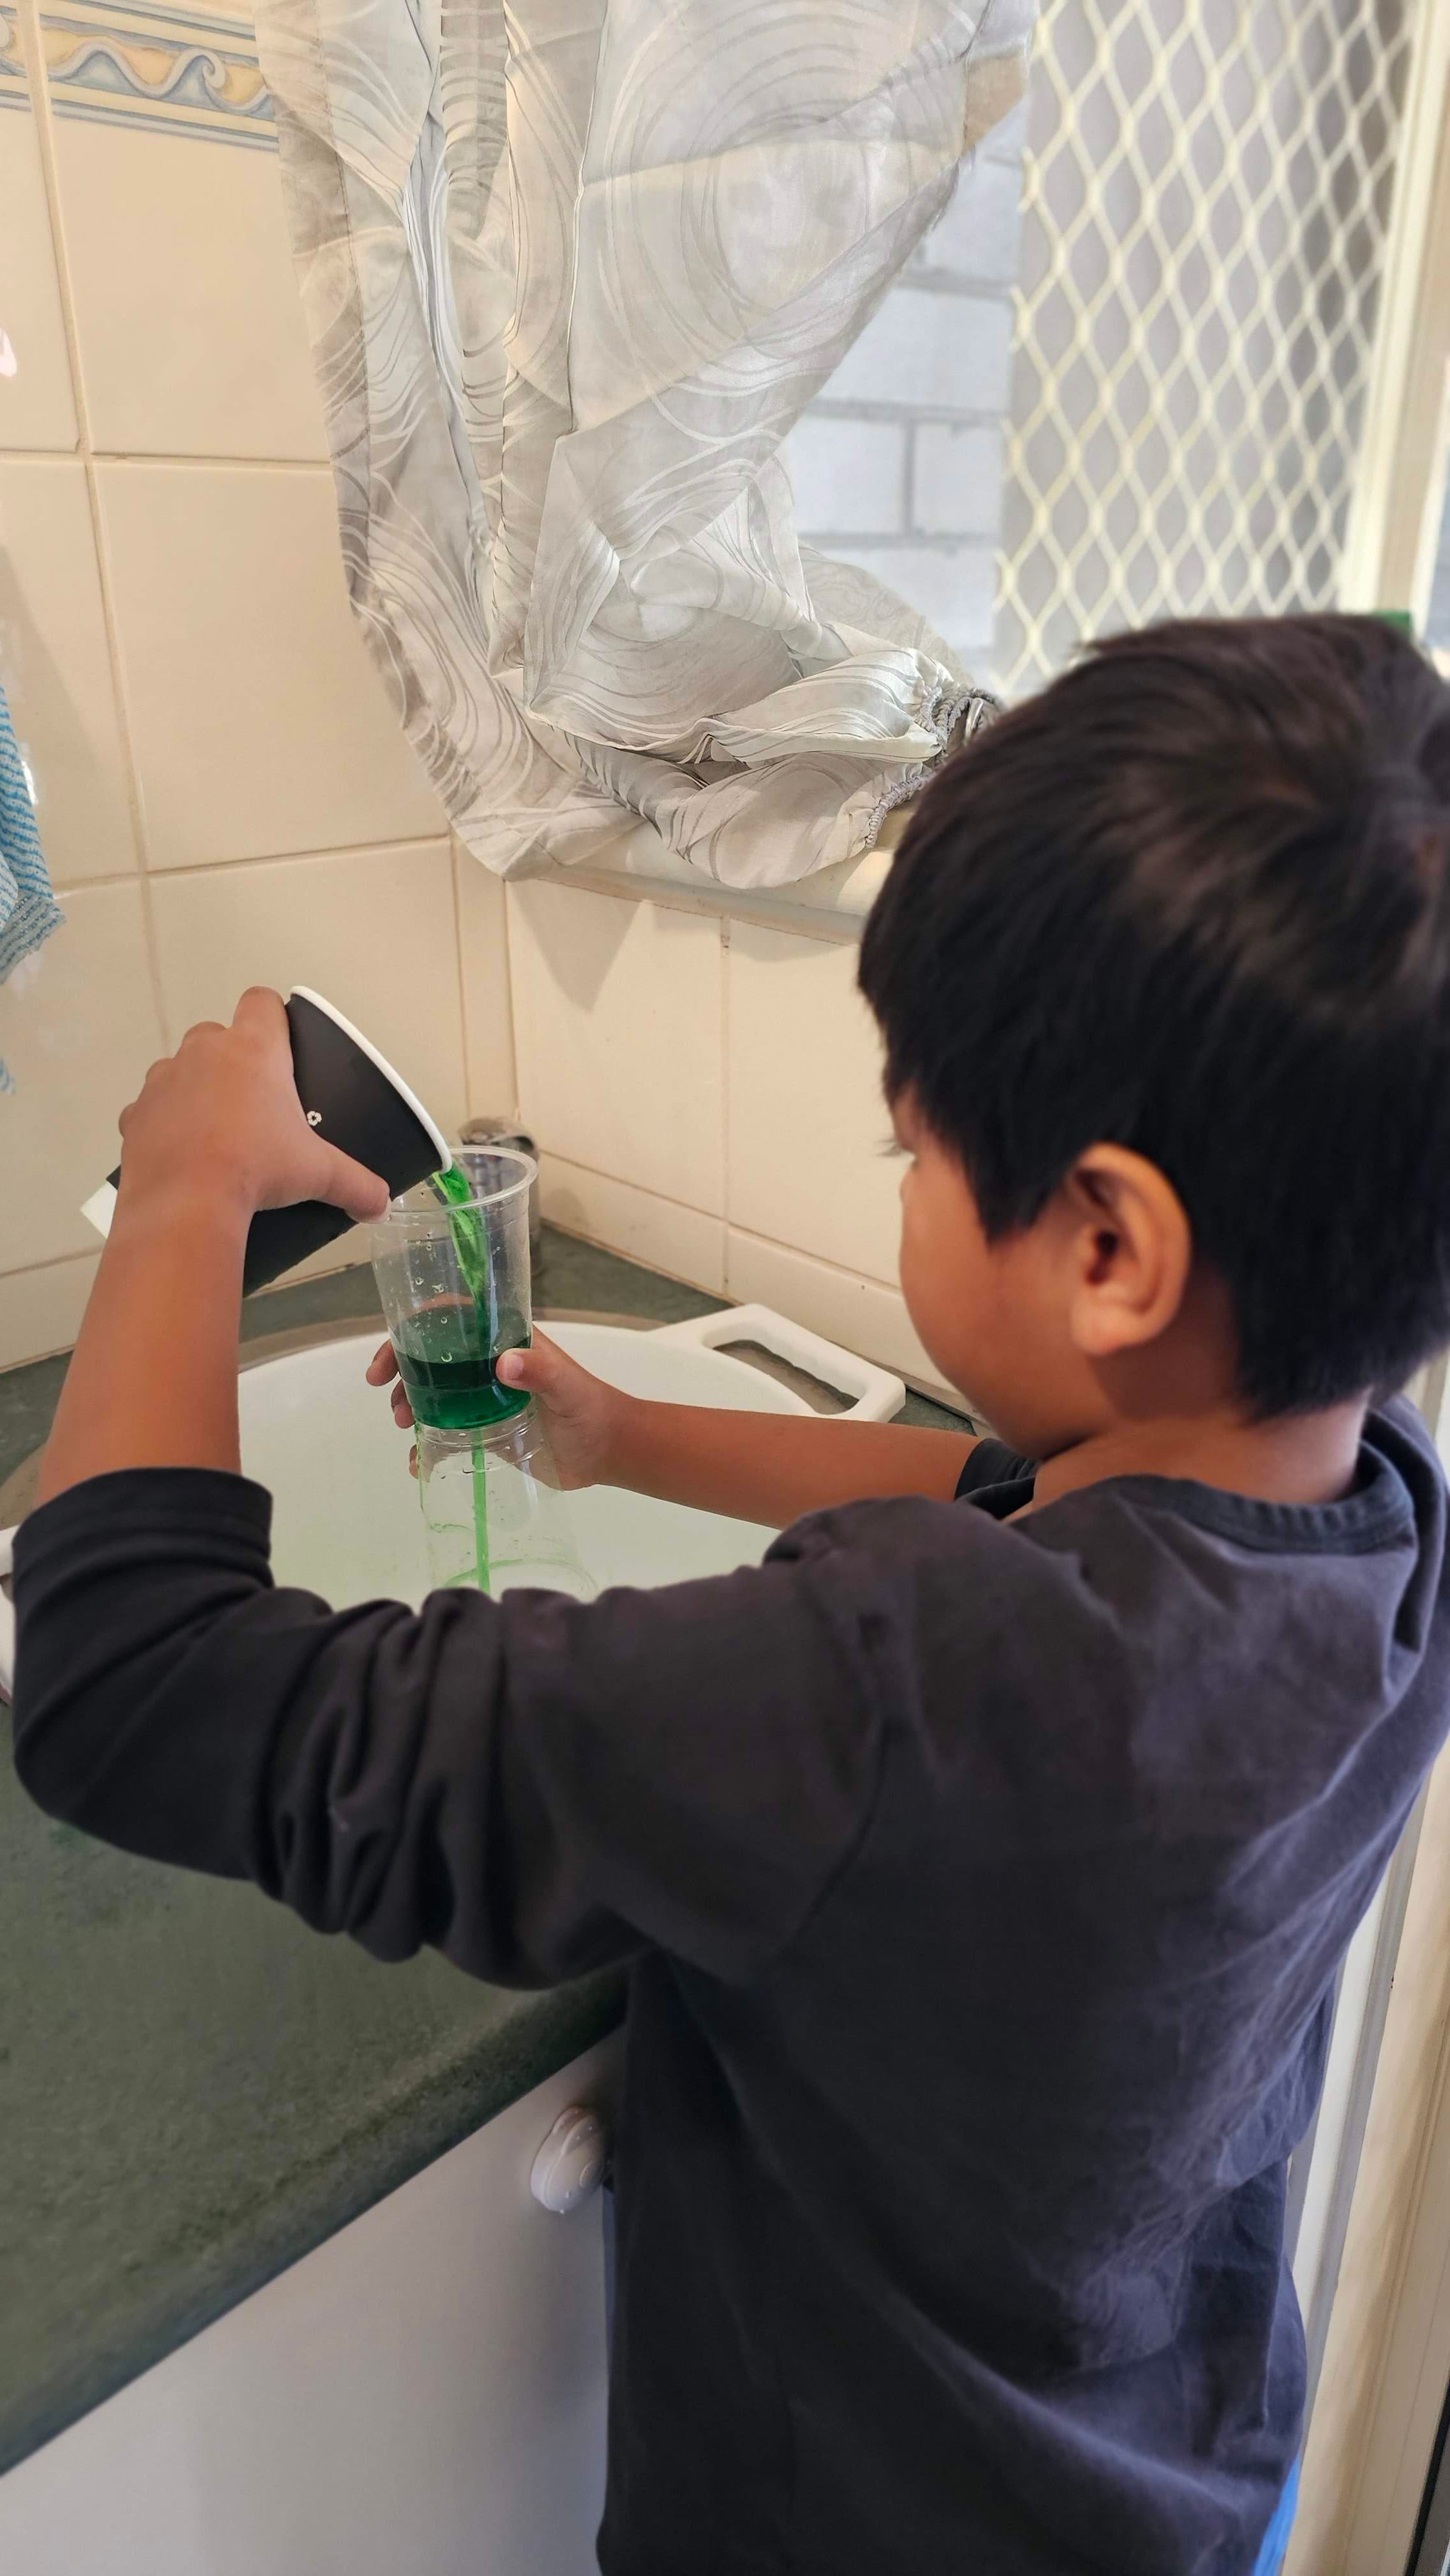
This experiment also symbolises something - Baking Soda by itself is just like a powdery substance and Vinegar by itself is just a liquid. But when they both are combined - BANG! A Volcano erupts! :)
In the previous article - we explored how we can do PAYG schedule variation with assets on negative gearing - in this article below - I try and explain how we can combine PAYG schedule variation with Salary Sacrifice to increase our nest egg in Super without dipping or reducing our cash flow. Here is the strategy for the Win-Win!
Not too long ago, a colleague of mine found himself in a really tough spot.
His wife had just lost her job due to a company restructure. Between their home loan and an investment property in Perth, the pressure was mounting fast. With two mortgages and only one income stream, stress became a constant companion. We were catching up over lunch when he finally opened up - he looked exhausted and scared.
He wasn’t just worried about the numbers in their bank account. He was carrying the weight of keeping everything afloat - his home, his investment, his family’s stability. And in that moment, he didn’t need sympathy - he needed clarity and options.
Based on the suggestion he spoke to his accountant about a PAYG withholding variation. It’s a simple but often overlooked strategy: if we’re expecting a tax refund at the end of the year (like many property investors are), we can apply to get that money in our pay check instead, month by month. That way, instead of waiting 12 months for a tax refund, we unlock that cash flow immediately.
He took the advice seriously. He applied, and sure enough, it boosted his monthly take-home pay. That extra cash helped him stay on top of loan repayments, cover essentials, and avoid the pressure of selling off the investment property at the wrong time.
Fast forward to today - his wife has just landed a new job (what a relief!), and they’re in a much more stable place financially. Not only did they hold onto the property, but with the recent growth in Perth’s housing market, they’ve also built over $100K in equity.
So, What’s Next?
Now that the dust has settled, we had another chat. The emotional rollercoaster of the past few months had given them something more than equity or income - it gave them clarity.
They weren’t just looking to survive anymore. They were ready to optimise.
With that additional monthly cash still coming in from the PAYG variation, we explored how they could redirect a portion of it into their super through salary sacrificing.
Here’s why:
Salary Sacrificing into Super – A quiet Power move
Tax Savings
Instead of being taxed at our marginal rate (say 34.5% or higher), any salary-sacrificed super contributions are taxed at just 15%. That’s a significant win, especially when we're earning a decent income.Concessional Contributions Cap
Every year, we can contribute up to $30,000 (including employer super) into our super at the concessional 15% tax rate. If we’re not maxing it out, we’re leaving long-term wealth on the table.Compound Growth
The earlier we start contributing, the longer our money has to grow. It’s like planting a tree - the sooner we do it, the sooner it provides shade.No Impact to Lifestyle
Since their cash flow had already increased thanks to the PAYG variation, they didn’t feel a pinch by diverting a portion of it into super. They weren’t sacrificing comfort - they were reallocating surplus.
A Simple Case Study: What Does $500 Salary Sacrifice Look Like?
Let’s say someone is earning over $180,000 per year, which places them in the top marginal tax bracket (45% + 2% Medicare Levy = 47%).
If they choose to salary sacrifice $500 per month into super:
Normally, $500 would be taxed at 47%, meaning $235 goes to tax, leaving just $265 in take-home pay.
Instead, by salary sacrificing, the $500 is taxed at just 15%, which is $75, and the full $425 goes into super.
Their monthly take-home pay drops by only $265, but they’ve added $500 to their super.
Tax saving? A solid $160 ($235-$75) per month, or $1,920 per year.
So, they’re giving up just $265 of spending money each month, but investing $500 in their future. That’s a powerful swap, especially if they’re already managing fine with their current budget.
And if they’re parking any savings in an offset account, they’re still ahead on interest savings too.
Step-by-Step Breakdown
1. Marginal Tax Rate for $180K+ Income:
The highest marginal tax rate in Australia is 45%, plus 2% Medicare Levy, totalling 47%.
2. Without Salary Sacrifice:
If you take $500 as salary, here’s what happens:
Taxed at 47% ⇒ $500 × 47% = $235 goes to tax.
Net in hand = $500 - $235 = $265.
3. With Salary Sacrifice:
$500 is contributed directly to super (pre-tax).
Taxed at 15% super concessional rate ⇒ $500 × 15% = $75.
Net amount going into super = $425.
4. Tax Saved:
You avoid paying $235 in personal tax, and instead pay $75 in contributions tax.
Tax saving = $235 - $75 = $160 per month.
From Survival Mode to Strategy Mode
Here’s what we love about this story: it didn’t end with just “things got better.”
It evolved into a mindset shift—from being stuck and reactive, to being informed and intentional.
They’re no longer feeling overwhelmed. They’re in control—with a growing property portfolio, improved cash flow, and now a retirement strategy that’s working quietly in the background.
And it all started with a conversation, and a small shift in awareness.
What We Can Take Away From This
There’s almost always a way through - but we need to know our options. Let’s talk to people. Read. Ask questions. Information is wealth.
Optimise, don’t just stabilise. Once we’ve created room in our finances, let’s not let it sit idle - put it to work for us.
Super is not just for “old people.” It’s one of the most tax-effective ways to build long-term wealth.
We don’t have to do this alone. Whether it's friends, advisors, or community - let’s surround ourselves with people who share ideas, not just opinions.
Next Step?
If we're feeling financially stable again - whether it’s from a pay raise, a new job, or even a refund - let’s consider using part of that extra cash to start contributing into super or pay off debt.
It doesn't have to be big. Even $100 a fortnight adds up. But that small move can mean the difference between coasting into retirement and walking in confident, prepared, and proud.
Credits / References: ChatGPT, Google, ATO, Learned experiences!