

By the end of this article, we hope to answer four simple questions:
What exactly do IVV and VAS own?
Why do we still invest in them even though we already own VGS?
How does our portfolio compares against the global economy of businesses.
Where do assets like Gold and Bitcoin fit into our overall portfolio?
And how did our portfolio flare from Aug 2022 till today!
When we first started investing, we assumed diversification meant buying as many different ETFs as possible.
One ETF from Vanguard.
One from iShares.
A technology ETF.
Maybe one focused on dividends.
Perhaps another on emerging markets.
And one all in like VDHG.
The more we bought, the more diversified we thought we were. And none of them were wrong - we had to make mistakes and learn from it to find what works for us.
And, it took us a while to realise that owning more funds doesn’t necessarily mean owning more businesses.
Sometimes, we’re simply buying the same companies wearing different clothes and paying more fees in crossovers too.
That was one of the biggest lessons we’ve learnt over the years.
First, a quick recap
In the previous article we spoke about VGS.
VGS gives us exposure to more than a thousand large companies across developed countries.
It’s our “own a slice of the developed world” ETF.
But if we looked a little closer, we’d notice something interesting.
Around 70% of VGS is already invested in the United States.
Which means companies like Apple, Microsoft, Nvidia, Amazon and Meta already make up a significant part of that portfolio.
So why buy IVV as well?
What does IVV actually own?
IVV tracks the S&P 500 Index.
Instead of owning over a thousand companies around the world like VGS, IVV focuses on roughly 500 of America’s largest listed companies.
If VGS is a world map...
IVV is a zoomed-in view of the United States.
It holds many of the companies we use almost every day.
Apple.
Microsoft.
Amazon.
Alphabet.
Meta.
Visa.
Costco.
Nvidia.
Broadcom.
And hundreds more.
The important thing we eventually understood was this.
IVV isn’t giving us completely new companies.
It’s giving us more exposure to the companies that have historically driven much of the world’s innovation and corporate profits.
In other words, we’re deliberately leaning a little more towards America.
Not because we know it will always outperform.
But because we believe many of the world’s most influential businesses will continue being built there for a long time.
Could that change?
Absolutely.
That’s exactly why we don’t put everything into IVV.
Then why own VAS?
If IVV is our slight overweight towards America...
VAS is our reminder not to forget home.
VAS tracks around 300 Australian companies.
Banks.
Mining companies.
Healthcare.
Retail.
Telecommunications.
Infrastructure.
Many Australians already have exposure to local property.
Many of us also work for Australian companies.
So on paper, we could argue we’re already heavily exposed to Australia.
We’ve had that debate ourselves many times.
So why keep buying VAS?
For us, there are three reasons.
The first is simplicity.
We live here.
We earn Australian dollars.
Many of our future expenses will also be in Australian dollars.
Having part of our investments producing income in the same currency feels comfortable.
The second is dividends.
Australian companies have traditionally paid relatively attractive dividends compared to many overseas markets.
Those dividends become another source of cash flow over time.
And finally...
There’s probably an emotional reason too.
There’s something satisfying about owning tiny pieces of companies we’ve grown up seeing all our lives.
Sometimes investing isn’t purely mathematical.
Sometimes psychology matters just as much.
So how does this all fit together?
If someone looked only at our ETFs, they might think we were trying to beat the market.
We’re actually trying to do the opposite.
We’re trying to build something simple enough that we’ll continue investing through good years and bad. In rain and shine. During Trump Tantrums and in War and in Recessions too.
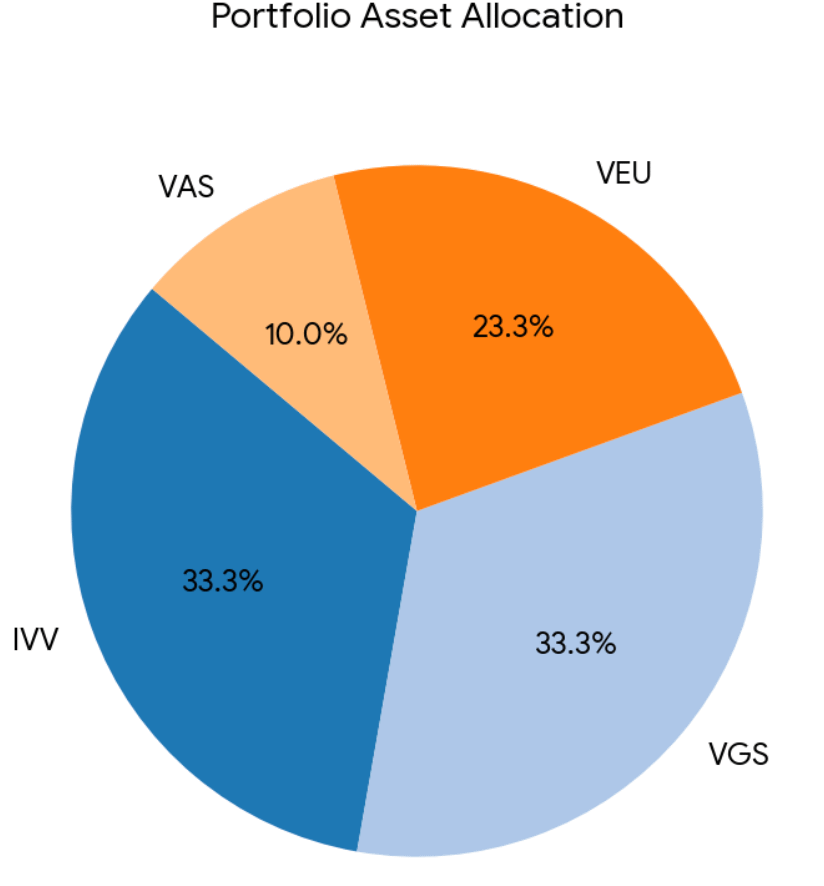
Today, our equity portfolio roughly looks like this:
VGS – our foundation. Exposure to developed markets across the world.
IVV – a little extra confidence in the United States.
VAS – keeping Australia as part of the journey.
VEU – exposure to emerging and international markets outside the US.
Could we simplify this even further?
Probably.
Would one ETF be enough?
Quite possibly.
We’ve simply chosen this mix because it helps us sleep well at night.
And we’ve learnt that’s often more important than squeezing out another 0.5% return.
My Portfolio and the World Economy
Here is how my portfolio looks when it’s distributed against against the geography of the world:
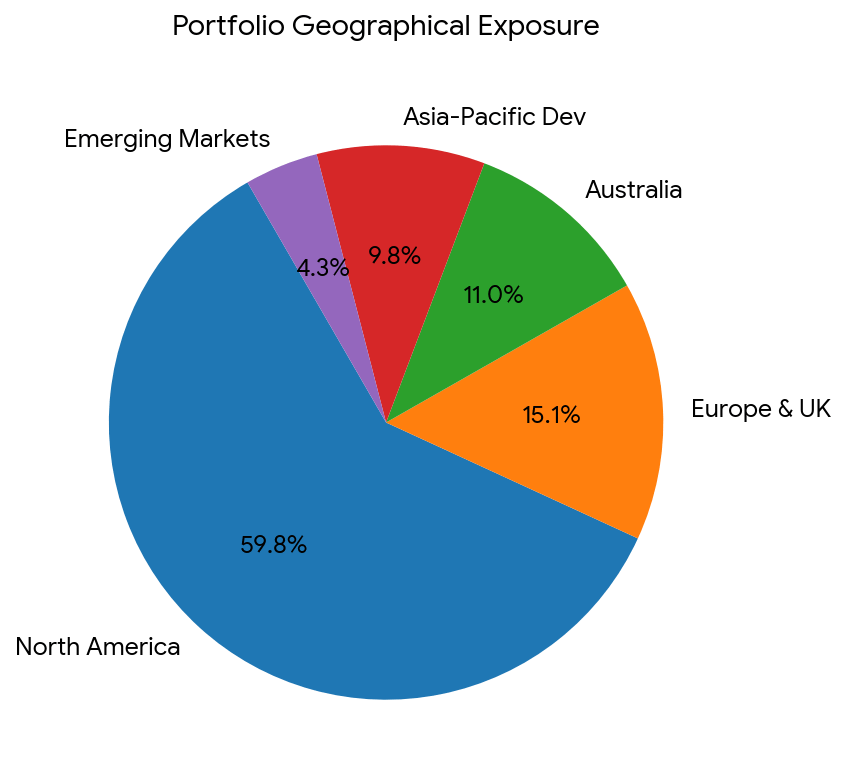
Putting it in a tabular format in comparing against the total global share market distribution
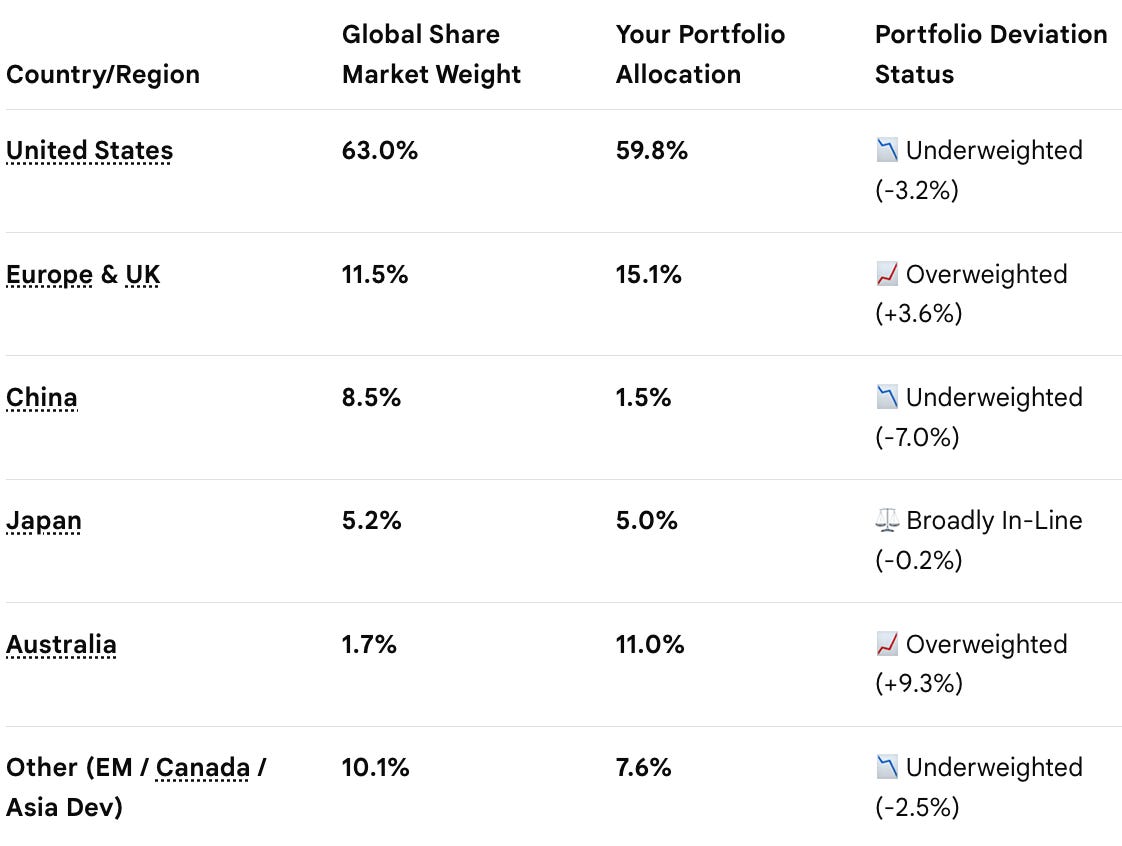
I’m less in China and more in Australia as a contrast - it’s a home bias plus can’t say no to franked dividends. And I don’t feel I’m missing out on China’s growth.
Putting that in a bar chart view - this is how it compares.
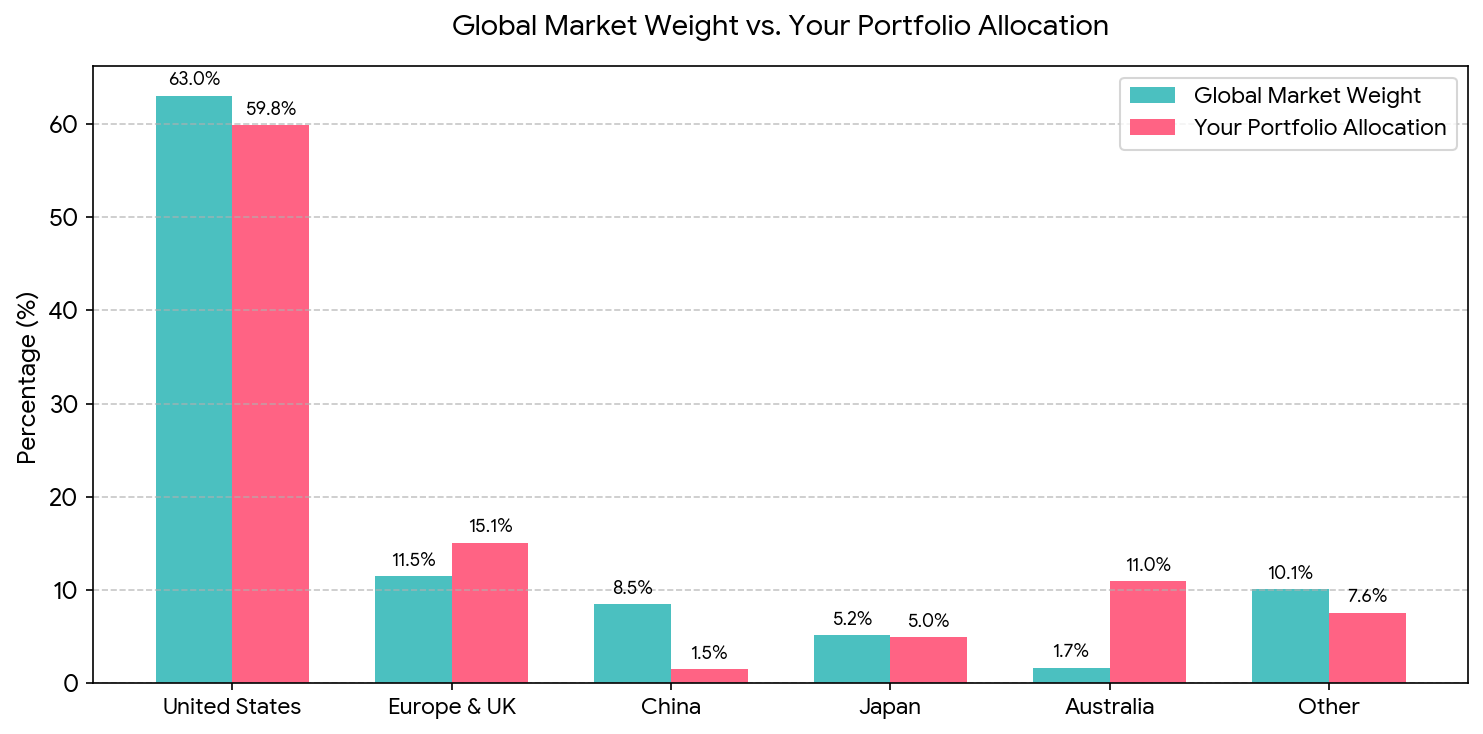
In summary my portfolio mirrors the world economy except less in China and more in Australia which is what I want.
What about Gold?
This is one investment we still go back and forth on.
Gold doesn’t produce earnings.
It doesn’t pay dividends.
It doesn’t invent new products.
It simply sits there.
Yet it has survived wars, recessions, inflation and financial crises for thousands of years.
We don’t see Gold as something that grows our wealth.
We see it as something that helps preserve it during uncertain times.
Whether that’s worth allocating part of a portfolio to is a personal decision.
For us, we have enough in precious metals and that’ll do.
And Bitcoin?
This one usually starts the most interesting conversations.
Some people believe Bitcoin will become digital gold.
Others believe it’s purely speculation.
The truth is... it’s somewhere in between.
What we do know is that technology continues to evolve, and Bitcoin has managed to survive for more than fifteen years despite countless predictions of its demise.
So we own a small allocation. And hopefully one day we have 1 bitcoin each for the kids & this is a long term play and I’ve no time horizon to it.
Small enough that if it went to zero, it wouldn’t change our family’s future.
But meaningful enough that if it became an important part of tomorrow’s financial system, we’d participate in that upside and our kids could thank us.
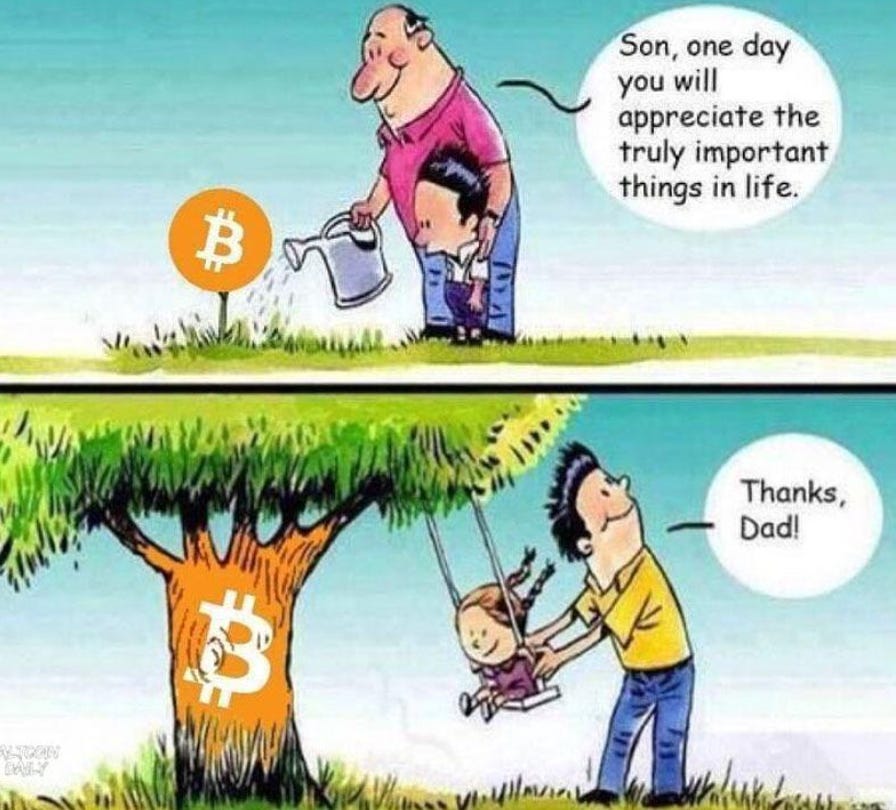
For us, Bitcoin isn’t replacing shares.
It’s simply a small bet on a future we can’t confidently predict.
Looking back
If there’s one thing we’ve slowly realised over the years, it’s that building wealth isn’t really about finding the perfect ETF.
It’s about finding a portfolio we can continue buying through recessions, bull markets, scary headlines and exciting headlines alike.
Our portfolio isn’t built because we know what will happen next.
It’s built because we accept that we don’t.
That’s probably the biggest mindset shift investing has given us.
We stopped trying to predict the future.
Instead, we started preparing for many possible futures.
If it’s going up - just continue DCA, if it’s going down due to Trump Tantrums - we add more if cash reserves permitting.
We simply stopped timing the market and just get on with one thing - that is we keep investing which is the only control that we have. What market does - it’s in nobodys control. So, why fret on things that we can’t control.
So, here is how our portfolio flared over this past 4 years since Aug 2022. Pretty happy with the results for keeping a passive investment.

Every dollar saved / invested is an employee that’s working hard to replace our income from our traditional job and that motivation keeps us going!
The birth of this post is out of my curiosity on understanding my own portfolio a bit deeper and better. And the series of question and answer style in this post is a result of a curated questions with AI.
If you’ve read this far - and if you want to jump on this asset - I’d still urge you to consider below - before hitting that buy button of ETFs.
Don’t have any credit card debts - as no matter how much the fund of your investment grows there is a bigger hole in your bucket if you hold credit card debt as that will be close to 20+% and it’s a blood sucking parasite. So, pay that off first.
Have sufficient amount of cash that you are comfortable enough to have in your emergency reserves - so that you don’t panic sell when the market does it’s “drunkard” behaviour.
And I don’t know your personal situation and circumstances and or your investment objectives - so, consider them before making this decision. This post is not a financial advice by any means. Consider this as an educational post.
Pearler referral link: And if you are new to investing and want to take a dip - here is my pearler link - this is the one that I use for my ETF purchases. If you are using this link - this doesn’t get me anything except for buying one free purchase of an ETF in the following month. So, thank you!
Advanced reading:
If you are keen to try out where or how much your holdings are getting invested into VGS - I’ve built a static github pages that can be used for reference.
https://somufun.github.io/portfolio_explorer/
Let’s say you have invested 10k into VGS and assume your favourite company is MSTR - and if MSTR trades at $95 and you have exposure only to $4.63 (based on your 10k invested) - then you still are exposed to that fund by pooling with others who are invested in VGS. This is the job for the fund manager whom we pay the 0.18% of MER to. He will pool with others and ensure that the allocation is taken into consideration at the weighted average.
And I genuinely thank my readers for encouraging me to keep doing these posts as it does take significant amount of time and it’s my labor of love. I will continue doing this as long as practically possible or until I run out of ideas.