

When I first started putting my money into the stock market, I felt like I was stumbling around in the dark. I wasn’t a finance expert; I was just someone who wanted their savings to work a little harder. Inspired by reading Rich Dad, Poor Dad book. The quote goes on to say
"Once a dollar goes into your asset column, it becomes your employee. The best thing about money is that it works 24 hours a day and can work for generations"
Over time, I’ve built a mix of four core building blocks: VGS, VAS, IVV, and VEU.
In this post, we are starting with VGS. Let’s look at Vanguard MSCI Index International Shares ETF (VGS), why I buy it, and exactly how it works behind the scenes.
Before we dig deeper - if you want to understand what is an ETF:
Where and how I found my ETF investment rhythm

Preface: Rethinking the Game We've Been Taught to Play
And why I don’t pick individual stocks anymore:
Our investment mistakes in stocks and what you can learn from it

Often a times we fail to remember that the mistakes are the best teachers. So has it been for us. We have lost a lot of money across various things in being able to realise what works for us and what doesn’t.
And now continue reading about VGS…
What exactly is VGS?
In the simplest terms, VGS is a giant, pre-packaged basket of shares. Instead of me trying to guess which companies in the world are going to succeed, VGS just buys all the biggest companies in the wealthiest countries on Earth (except Australia, because I have a different basket for home turf).
Why is it in my portfolio?
I hold VGS because it acts as my global safety net.
If I only bought Australian shares, I’d be putting all my eggs in one geographic basket. Australia only makes up about 2% of the global stock market. By holding VGS, my money is spread across roughly 1,200 to 1,400 different companies in 22 different developed countries. If the Australian economy has a tough year, my VGS basket is busy making money in the US, Japan, France, and Canada to balance it out.
The VIP List: How do companies and countries get in?
This is where it gets really interesting. There isn’t a guy in a suit sitting at a desk subjectively picking which companies are “good” or “bad.” It is entirely run by strict mathematical rules.
Here is how a country and a company make it into the VGS basket, explained as simply as possible:
1. The Country Test (The Rich Treehouse Club)
Before a company can even be considered, its home country has to be invited into the “Rich Country Club” (officially called a Developed Market).
Imagine a super exclusive treehouse. To get in, a country has to prove that its citizens have a very high average wealth, and they have to prove they can maintain that wealth for at least three years in a row. They also have to prove their rules are safe and fair for regular investors like us.
Because the rules are so strict, only 22 countries make the cut for this specific basket. This is why booming places like China and India aren’t in VGS - they are still growing and haven’t passed the final treehouse wealth test yet. To be in the top elite 22 countries - we have to take all the money everyone in the country makes, put it in a giant piggy bank, and divide it equally among all the people and that has to surpass the threshold. Given the population of India and China are high - they are still classified as Emerging Markets.
2. The Company Test (The 85% Candy Bowl)
Once a country is in the club, how do its companies get chosen? Imagine a giant bowl of Halloween candy that represents all the money in that country’s stock market.
The basket automatically scoops up the massive King-Sized chocolate bars first (the gigantic companies like Apple and Microsoft).
Then it scoops up the regular candy bars (medium companies).
It keeps scooping until the candy in its bag equals exactly 85% of the total weight of the original bowl.
It leaves all the thousands of tiny, loose Skittles (the small companies) behind. If a company is big enough to be part of that heavy top 85%, it gets a ticket into VGS.
The “What If” Worries: Can VGS go bust and will I lose my money?
This is the exact question that used to keep me up at night. What if Vanguard (the company that runs VGS) goes bankrupt? Or what if the stock market crashes? Let’s break down both fears.
Fear 1: What if Vanguard goes bust?
If Vanguard, the company, completely goes bankrupt tomorrow, our money is safe.
Here is a fun secret about how ETFs work: Vanguard doesn’t actually hold our shares. By law, they have to use an independent security guard called a “Custodian” (often a massive global bank like J.P. Morgan). The Custodian holds the candy bowl in a totally separate vault. If Vanguard goes out of business, the Custodian still holds all our pieces of Apple, Microsoft, and Toyota. They would simply hand the management of our candy bowl over to a new company, or sell the candy and give us the cash. We do not lose our shares just because the manager goes bust.
Fear 2: What if the market crashes and I lose my capital?
This is a different story. If the global stock market goes down, the value of VGS goes down with it. It happens, and it will happen.
But here is the trick: when the market drops, we haven’t actually “lost” anything unless we panic and sell. We still own the exact same amount of candy; it’s just that the current price tag someone is willing to pay for our candy bowl is temporarily lower. The very own fundamental economics of demand vs supply. When the demand is more - the price is high, when the demand is less the prices are low.
Near Halloween times - the shops and stores will all be selling the halloween costumes and decorations but right after the day Halloween is past - they all will be sold at 50% or more discount in the same shelves.
Demand vs Supply.
Historically, the world economy has always recovered and grown over the long term because human beings keep inventing things, building businesses, and buying stuff. So yes, the value will go up and down, but because VGS owns 1,400 of the world’s best companies, the only way VGS goes to zero is if all 1,400 of those companies go bankrupt at the exact same time. If that happens, the world has ended, and money won’t matter anyway!
The Nitty-Gritty: Fees and Performance
As an everyday investor, cost is everything. The more I pay in fees, the less money stays in my pocket to compound and grow.
The Cost (MER):
VGS has a Management Expense Ratio (MER) of 0.18% p.a.
In simple terms, this means for every $10,000 I have invested in VGS, Vanguard charges me just $18 a year to manage it, automatically reinvest the dividends, and keep the candy bowl perfectly balanced. It is incredibly cheap.
The Performance:
Historically, letting the world’s biggest companies do the heavy lifting has worked out pretty well. Here is what the total returns (which includes both the share price growing and the dividends paid out) have looked like as of mid-2026:
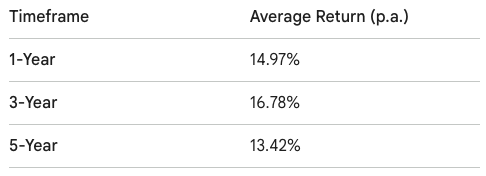
Note: The share market goes up and down, so past performance doesn’t guarantee the future, but this shows the historical power of owning a slice of the developed world.
Why do I own IVV and VGS as there is a lot of overlap?
Yes, 70% of VGS is US top companies - but then the devil is in the details. There are few companies that they don’t make it into IVV. Because the IVV mirrors S&P 500 and that has much more strict criteria to be considered in it. This criteria rules out companies like SpaceX, MSTR etc., which I think it’s worth taking that bit of a risk rather than holding the individual stock. It’s just that adventure bits of not missing out doesn’t kick in to lure me back into buying something hot at that moment.
Why do I own VGS and VEU as there is a lot of overlap?
Again, yes, but then the remaining 30% of VGS outside of US doesn’t include the emerging markets like India, China and Brazil. VGS holds top 22 countries while VEU holds top 49 countries. So, this gives me exposure to the growing economy like India and hence the double dip.
For me, VGS is the ultimate “set and forget” tool. I don’t need to read financial reports in Japanese or worry about a specific tech company going bankrupt in the US. The index rules automatically clean house - if a company shrinks, it falls out of the basket; if a new company becomes a giant, it gets added.
I just keep adding my savings, and let the global economy do the rest.
The birth of this post is out of my curiosity on understanding my own portfolio a bit deeper and better. And the series of question and answer style in this post is a result of a curated questions with AI in the morning.
If you’ve read this far - and if you want to jump on this asset - I’d still urge you to consider below - before hitting that buy button of VGS.
Don’t have any credit card debts - as no matter how much the fund of your investment grows there is a bigger hole in your bucket if you hold credit card debt as that will be close to 20+% and it’s a blood sucking parasite. So, pay that off first.
Have sufficient amount of cash that you are comfortable enough to have in your emergency reserves - so that you don’t panic sell when the market does it’s “drunkard” behaviour.
And I don’t know your personal situation and circumstances and or your investment objectives - so, consider them before making this decision. This post is not a financial advice by any means. Consider this as an educational post.
Pearler referral link: And if you are new to investing and want to take a dip - here is my pearler link - this is the one that I use for my ETF purchases. If you are using this link - this doesn’t get me anything except for buying one free purchase of an ETF in the following month. So, thank you!
Advanced reading:
If you are keen to try out where or how much your holdings are getting invested into VGS - I’ve built a static github pages that can be used for reference.
https://somufun.github.io/portfolio_explorer/
Let’s say you have invested 10k into VGS and assume your favourite company is MSTR - and if MSTR trades at $95 and you have exposure only to $4.63 (based on your 10k invested) - then you still are exposed to that fund by pooling with others who are invested in VGS. This is the job for the fund manager whom we pay the 0.18% of MER to. He will pool with others and ensure that the allocation is taken into consideration at the weighted average.